

Being in a car accident is stressful enough, but discovering the at-fault driver has little or no insurance can turn a difficult situation into a financial nightmare. How do you cover your medical bills, lost wages, and other damages? This is where Uninsured/Underinsured Motorist (UM/UIM) coverage becomes your most critical asset.
Many drivers in California are unsure about this vital protection. “How much uninsured motorist coverage do I need?” is a question we hear constantly. While the state has minimum requirements, they are dangerously low and simply not enough to protect you and your family.
This guide will walk you through exactly what you need to know about uninsured motorist coverage in California, how much you should carry, and the serious risks you face without it.
Why Uninsured Motorist Coverage is Non-Negotiable in California
We recommend a minimum of $100,000 in Uninsured/Underinsured Motorist (UM/UIM) coverage, but carrying $250,000 is a safer bet if you can afford it.
Here’s why: California has one of the highest costs of living in the United States, yet our required auto insurance liability limits are among the lowest. The state only requires drivers to carry a mere $15,000 for the injury or death of one person.
What does $15,000 actually cover after a moderate to serious accident? Not much. Consider these average costs our clients face after a crash in California:
- Ambulance Ride: $2,500 – $3,000
- Emergency Room Visit: $2,500 – $5,000
- X-rays, MRIs, or CT Scans: $500 – $5,000+
- Surgery: $5,000 – $25,000+
- Overnight Hospitalization: $5,000 – $10,000 PER NIGHT
As you can see, the costs of basic emergency care can easily exceed the $15,000 state minimum. This doesn’t even account for follow-up appointments, physical therapy, or lost income from being unable to work. If the at-fault driver only has the minimum coverage, their policy will be exhausted quickly, leaving you to pay the rest out-of-pocket.
The High Cost of Inadequate Coverage
Choosing to save a few dollars by skimping on UM/UIM coverage is one of the biggest financial risks a driver can take. Without it, you could face:
- Mounting Medical Debt: Your health insurance may cover some initial costs, but you will likely be responsible for deductibles, co-pays, and services that aren’t covered.
- Reimbursing Your Health Insurer: If you receive a settlement from the at-fault driver, your health insurance company has a right to be reimbursed. After paying them back from a meager $15,000 settlement, you could be left with nothing for your pain and suffering.
- No Compensation for Pain and Suffering: A small liability policy leaves no room to compensate you for the physical pain and emotional distress caused by the accident.
- Inability to Recover Lost Wages: If you can’t work due to your injuries, you could lose your income with no way to recover it from the underinsured driver.
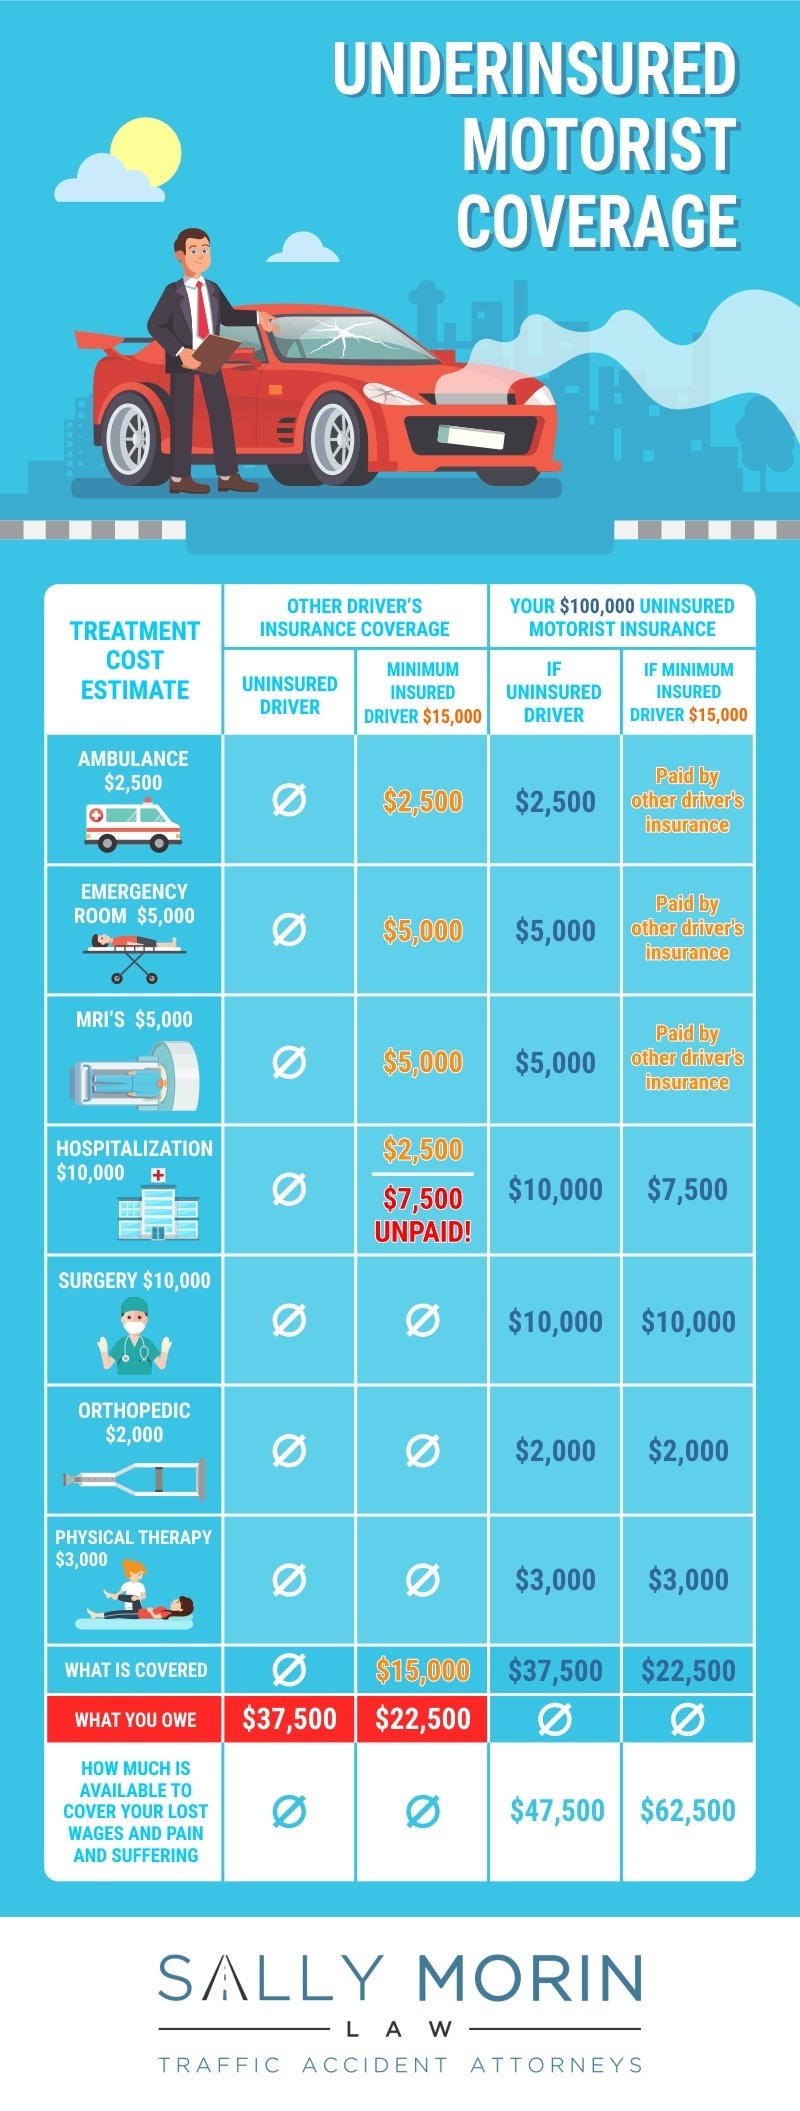
Underinsured Motorist Coverage
There’s no way that somebody’s $15,000 state minimum liability coverage is going to be enough to pay for the bare minimum medical needs if you are in even a moderate – let alone serious – personal injury accident.
Even if you are lucky enough to get out of an accident relatively unscathed, you are still looking at around $5-10,000 just to get checked out by a qualified emergency medical professional.
That is why it’s important to get uninsured motorist insurance coverage at the highest possible amount you can afford. Note that your liability limits will have to be set at this same amount.
Don’t Forget Property Damage (UMPD)
While your medical bills are the top priority, what about your car? If an uninsured driver hits you, you could be left without a vehicle and no way to pay for repairs. This is where Uninsured Motorist Property Damage (UMPD) coverage comes in.
UMPD is a separate coverage that pays for repairs to your vehicle if it’s damaged by a driver with no insurance. In California, UMPD coverage has a limit of $3,500.
Key things to know about UMPD:
- It’s an alternative to Collision: You generally cannot use both UMPD and your Collision coverage for the same claim.
- It’s for the uninsured, not underinsured: UMPD typically only applies when the at-fault driver is completely uninsured.
- The deductible is lower: For many, the main benefit is the lower deductible. UMPD deductibles are often much smaller than standard collision deductibles.
If you don’t have collision coverage, adding UMPD is an absolute must. If you do have collision, weigh the cost against the benefit of a lower deductible in an uninsured driver scenario.
The Cost vs. The Value: How Much Are UM Premiums?
A common question we hear is, “How much does uninsured motorist coverage cost?” While the exact premium depends on your driving record, vehicle, and insurance carrier, most drivers are surprised at how affordable it is.
Typically, increasing your UM/UIM coverage from the state minimum (or zero) to a substantial amount like $100,000 or $250,000 adds a relatively small amount to your monthly or semi-annual premium.
Think of it this way: The cost of adding robust protection is often less than a single tank of gas or a few cups of coffee per month. When you compare that minor cost to the risk of facing $50,000+ in medical and repair bills that an uninsured driver leaves you with, the value is undeniable. It’s the highest-value insurance you can buy.
What Our Clients Are Saying
“Sally Morin, and Annie in particular, were very helpful in getting us a more than fair settlement of our case. Annie was very patient and thorough, and walked us through the process every step of the way. She was very quick to respond to our questions, and was always in communication with us. What could have been a frustrating and intimidating process turned out to be much less than that, thanks to Annie. I would wholeheartedly recommend Sally Morin Law, and Annie in particular, to anyone who needs a competent and ethical personal injury lawyer.” Louise N. Yelp
Read Louise N.‘s review of Sally Morin Personal Injury Lawyers on Yelp
I have spent a while trying to find attorneys for an uninsured motorist accident a while back. Some people thought my case was too small (because I wasn’t seriously injured!) and some gave me fairly bad vibes.
Rebecca was recommended to me by another attorney and has been fantastic:
- She is super honest, straight forward, and direct
- She is responsive and timely
- She has a lot of experience. She had dealt with the exact same injury that I suffered and had some great advice.
She decided this case wasn’t a good fit for either of us, but gave me a ton of extremely useful advice and perspective.I would absolutely work with again if I had an opportunity.
David K, Yelp
Read David K.‘s review of Sally Morin Personal Injury Lawyers on Yelp
UM/UIM vs. Liability vs. Collision Coverage
Insurance policies can be confusing. Many drivers mistakenly believe “full coverage” automatically protects them from everything. Here’s a clear breakdown of who and what is covered by these key policy types.
| Coverage Type | What It Covers | Who It Pays For | When It’s Used |
| Bodily Injury Liability | Medical bills, lost wages, and pain & suffering for others. | Other people you injure in an accident. | When you are at fault for the accident. |
| Collision Coverage | Repair or replacement of your own vehicle after an accident. | You and your vehicle. | When you are in an accident, regardless of who is at fault. |
| Uninsured/Underinsured Motorist (UM/UIM) | Your medical bills, lost wages, and pain & suffering. | You and your passengers. | When an at-fault driver has no insurance or not enough insurance to cover your bills. |
Demonstrating Success: A Case Result Example
Understanding the value of proper representation is key. While every case is unique, our experience in handling complex personal injury claims allows us to fight for the maximum compensation our clients deserve.
For example, we secured a $450,000 settlement for a client who was struck by a vehicle while walking in a crosswalk. The driver’s insurance company initially offered a low settlement that wouldn’t have covered our client’s extensive medical treatments and future needs. We meticulously built a case, demonstrating the full extent of our client’s damages and the driver’s negligence, ultimately securing a settlement that provided financial security for their recovery.
This is the level of dedication we bring to every case, whether it involves an uninsured driver, a complex liability dispute, or a catastrophic injury.
How to Choose the Right Personal Injury Lawyer
After an accident, choosing the right lawyer can feel overwhelming. To help you make an informed decision, use the interactive tool below to understand the key qualities to look for in a personal injury attorney.
How to Choose the Right Lawyer for You
Frequently Asked Questions (FAQ)
We’ve compiled answers to the most common questions about uninsured and underinsured motorist coverage in California.
If You Need Help with a Traffic Accident Case, We Are Here!
If you or anyone you care about is ever seriously injured in a bike, car, motorcycle, pedestrian or Uber accident you need an experienced personal injury attorney to fight for you and get the significant settlement you’re entitled to.
You need the experienced California personal injury lawyers at Sally Morin Personal Injury Lawyers. Get a FREE online case evaluation now to see if we can help


