
One of the biggest concerns for many drivers in California is car insurance premium increases after an accident. When a person is at fault, it is understandable that the consequences would involve an increase in their insurance rate. But what if the driver is not at fault?
At Sally Morin, as California car accident lawyers, our clients often ask us, “How much will my insurance go up after an accident?” or “Will my premiums go up if I was not at fault?” So we decided to answer these questions and a few more by putting together this list of frequently asked questions regarding insurance rates and car accidents.
If you’ve been seriously injured in a car accident, before you read on about your insurance, you should really speak with an expert car accident lawyer to protect your rights! Call us at 877-380-8852 or contact us online for a free case evaluation.
How much does car insurance increase after an accident?
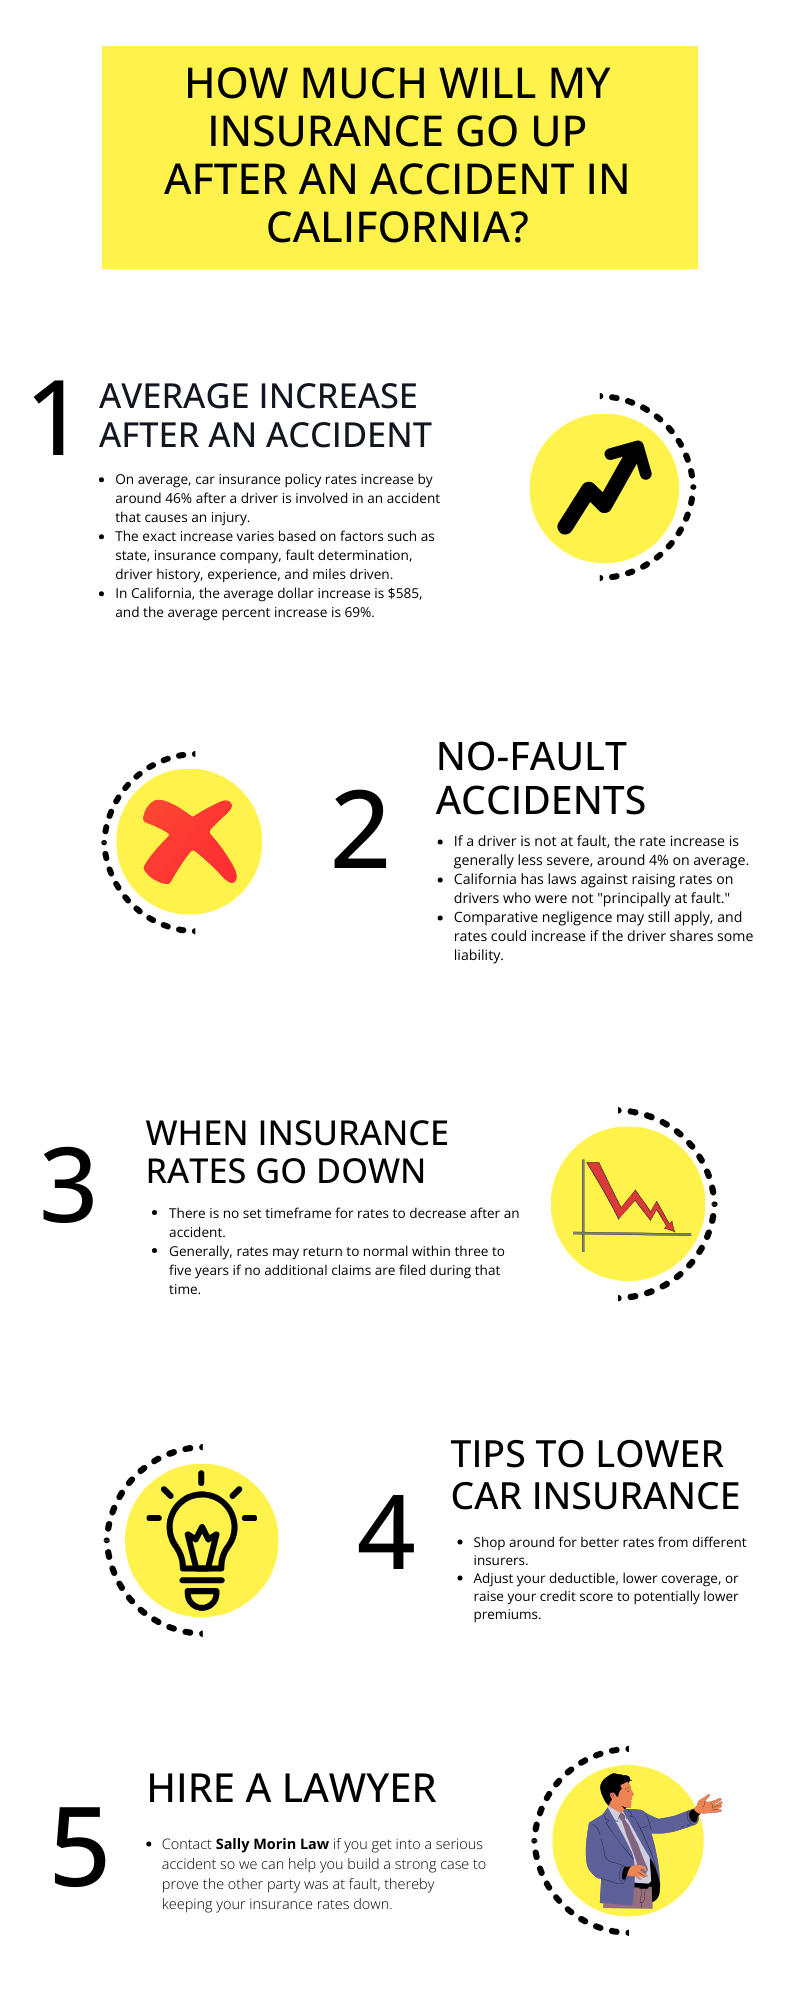
When you are deemed at fault for an accident, your insurance premium will almost certainly increase. For 2025, national data shows that drivers can expect an average auto insurance increase of 44% to 49% after an at-fault accident (Source: Bankrate and ConsumerShield).
In California, this rate hike is often more severe due to higher living costs and traffic density. While a precise average percentage for 2025 is still emerging, it is expected to be significant, especially with the new liability laws (more on that below). The exact amount your insurance will go up depends on several factors:
- Your Insurance Carrier: Each company assesses risk differently. One provider might increase rates by 30%, while another could raise them by over 70% for the same type of incident.
- Severity of the Accident: A minor fender-bender will have a smaller impact on your premium than a major collision resulting in significant property damage and bodily injury.
- Your Driving History: A driver with a previously clean record will likely see a smaller increase than someone with multiple accidents or traffic violations. Teenage insurance rates after an accident are often subject to the steepest increases.
- Accident Forgiveness: Some policies include “accident forgiveness,” which may prevent a rate increase after your first at-fault accident.
This increase typically stays on your record and affects your premiums for three to five years.
Important: California’s New Minimum Insurance Requirements for 2025
A major change has taken effect in 2025 that impacts every driver in the state. For the first time in decades, California has increased the mandatory minimum liability insurance limits.
As of January 1, 2025, the new minimums are:
- $30,000 for bodily injury or death to one person (up from $15,000).
- $60,000 for bodily injury or death to more than one person in a single accident (up from $30,000).
- $15,000 for property damage (up from $5,000).
(Source: California Department of Insurance). This change was made to provide better financial protection and account for the rising costs of medical care and vehicle repairs. While this offers greater security, it also means that insurance companies are taking on more risk, which will likely translate to higher premium increases after at-fault accidents.
What Our Clients Say
Navigating the aftermath of an accident is challenging, but you don’t have to do it alone. Here is what some of our clients have to say about their experience with our firm:
“I can’t imagine what I would have done without Sally Morin Law. After my accident, I was in the hospital for three weeks in a rehab for three more weeks back in the hospital for another month and then more rehab. During the whole time, Sally Morin helped me figure everything out and I never had to worry about, you know, how I was gonna get my medical bills paid and, you know, who was dealing with insurance companies and all kinds of stuff. I just got to deal with making sure that I was recovering and, uh, at the end of everything, uh, that I was healthy and okay” – Kyle B. (via YouTube)
“If you’re injured at all, I’d definitely recommend Sally Morin as a lawyer to speak with. Even if she doesn’t take your case, she’ll at least push you in the right direction.” – Reddit Testimonial
Comment
byu/Broad_Primary_8360 from discussion
inBAbike
Will My Insurance Go Up if the Accident Was Not My Fault?
This is a common source of anxiety. Fortunately, California has specific laws to protect drivers in this situation. Thanks to Proposition 103, an insurer cannot legally raise your premium for an accident unless you were “principally at fault” (meaning 51% or more responsible).
Therefore, if the other driver was 100% at fault, your insurance rate should not increase. However, California is a pure comparative negligence state. This means fault can be shared. If you are found to be partially at fault (e.g., 20% responsible), your insurance company could justify a rate increase.
When does car insurance go down after an accident?
There is no set timeframe for when insurance rates go back down after an accident. But the general rule of thumb is that the longer it has been since you were involved in an accident and filed a claim, the lower your rates will be.
Rates typically go up immediately after a crash and will return to normal within three to five years. But again, this only applies if you file no other claims during that time. If you do file another claim or are involved in another accident, it will take longer for your rates to go back down, and you will likely face more increases.
Luckily, there are tips and tricks for drivers who are interested in lowering their rates. These are not foolproof, as, again, numerous individual factors can affect your policy rate. Still, on average, these can help.
How to lower car insurance after an accident:
- Shop around for better rates. No two insurers are the same. So if you are wondering how to claim insurance after an accident or how to get lower rates, the key is to do your research and look into different insurance companies.
-
- Adjust your deductible. A lower deductible comes with its risks because it means you will have higher out-of-pocket expenses if something happens. But, it will at least lower your premiums.
- Lower your coverage. Similar to lowering your deductible, if you lower your primary coverage amounts, this will also lower your premiums. Just make sure you abide by your state’s minimum coverage requirements.
- Raise your credit score. Some insurance companies will reward policyholders with lower premiums when they have good credit. This will not work with every insurer, but it is a potential option.
A Real-Life California Car Accident Settlement Example
The right legal representation can make a monumental difference in your recovery.
$525,000 Car Accident Settlement: A 34-year-old Bay Area woman suffered serious injuries in a high-speed rear-end car accident. She faced a long, painful recovery and nearly $1 million in medical bills. The experienced California car accident settlement team at Sally Morin Personal Injury Lawyers took charge, securing a $525,000 settlement. This put over $321,192 directly in her pocket after her medical expenses were paid. Today, she is healed and living her life to the fullest.
Learn More
Calculate Your Potential Settlement
Seeing a successful settlement is one thing, but understanding what the details of your case could mean is the most important step. While every case is unique, our settlement calculator can help you get a preliminary estimate of what your claim could be worth based on factors like medical bills, lost wages, and property damage.
This tool is designed to give you a starting point and empower you with information.
Personal Injury Settlement Calculator
Disclaimer: This calculator provides an estimate for informational purposes only and is not a guarantee of a specific outcome. The most accurate valuation requires a detailed consultation with an experienced attorney.
Step-by-Step Guide: Key Rules to Follow After an Accident
Knowing how to react after an accident can protect your safety, your rights, and your finances.
- Step 1: Ensure Safety. Move to a safe location if possible, check for injuries, and call 911 immediately if anyone is hurt.
- Step 2: Report the Accident. Report the accident to the police. A police report is a crucial piece of evidence. You must also report any accident involving injury, death, or property damage over $1,000 to the California DMV within 10 days using the SR-1 form.
- Step 3: Exchange Information. Get the other driver’s name, contact information, driver’s license number, license plate number, and insurance policy details.
- Step 4: Document Everything. Take photos and videos of the accident scene, vehicle damage, road conditions, and any visible injuries. Talk to witnesses and get their contact information.
- Step 5: Seek Medical Attention. Even if you feel fine, see a doctor. Some serious injuries have delayed symptoms.
- Step 6: Contact a Car Accident Lawyer. Before speaking to any insurance adjuster, consult with an experienced personal injury attorney. An attorney can handle communication with insurers and protect you from saying something that could harm your claim.
Frequently Asked Questions (FAQ)
Here are answers to some of the most common questions we receive based on 2025 data.
Questions To Ask an Insurance Adjuster After an Accident
If you have questions about insurance after a car accident, you can speak to a car accident attorney or your insurance adjuster. Just make sure not to admit fault when talking to the insurance company, as they could use it against you.
Pertinent questions to ask could include:
- Will you raise my rates?
- How much will my rates increase after an accident?
- Do you have a safe-driving program that could reduce my rates?
- How does my claim get paid?
- Will you give me copies of the documents involved or “index” information concerning my claim so I can verify my rate?
Please be advised that the following topic is for informational purposes only. If you need further assistance regarding this particular topic, but do NOT have a serious injury accident case, you can contact your local Bar Association for a referral to an attorney who may be able to address your inquiry in more detail. If you have a serious injury accident…
We Handle Your Accident Claim So You Can Focus On Your Life
If you have questions or concerns about your car accident claim and insurance rates, the accident attorneys at Sally Morin can assist you. We understand how frustrating it can be to have your premiums go up after an accident. If you suspect your insurer is unlawfully raising your rates or denying your claim, we can protect your rights.
We truly care about the people of California. Call us at 877-380-8852 or contact us online today for a free case evaluation.


